Chasing Private Information
Review of Financial Studies, 2019 Part of Informed trading
Abstract
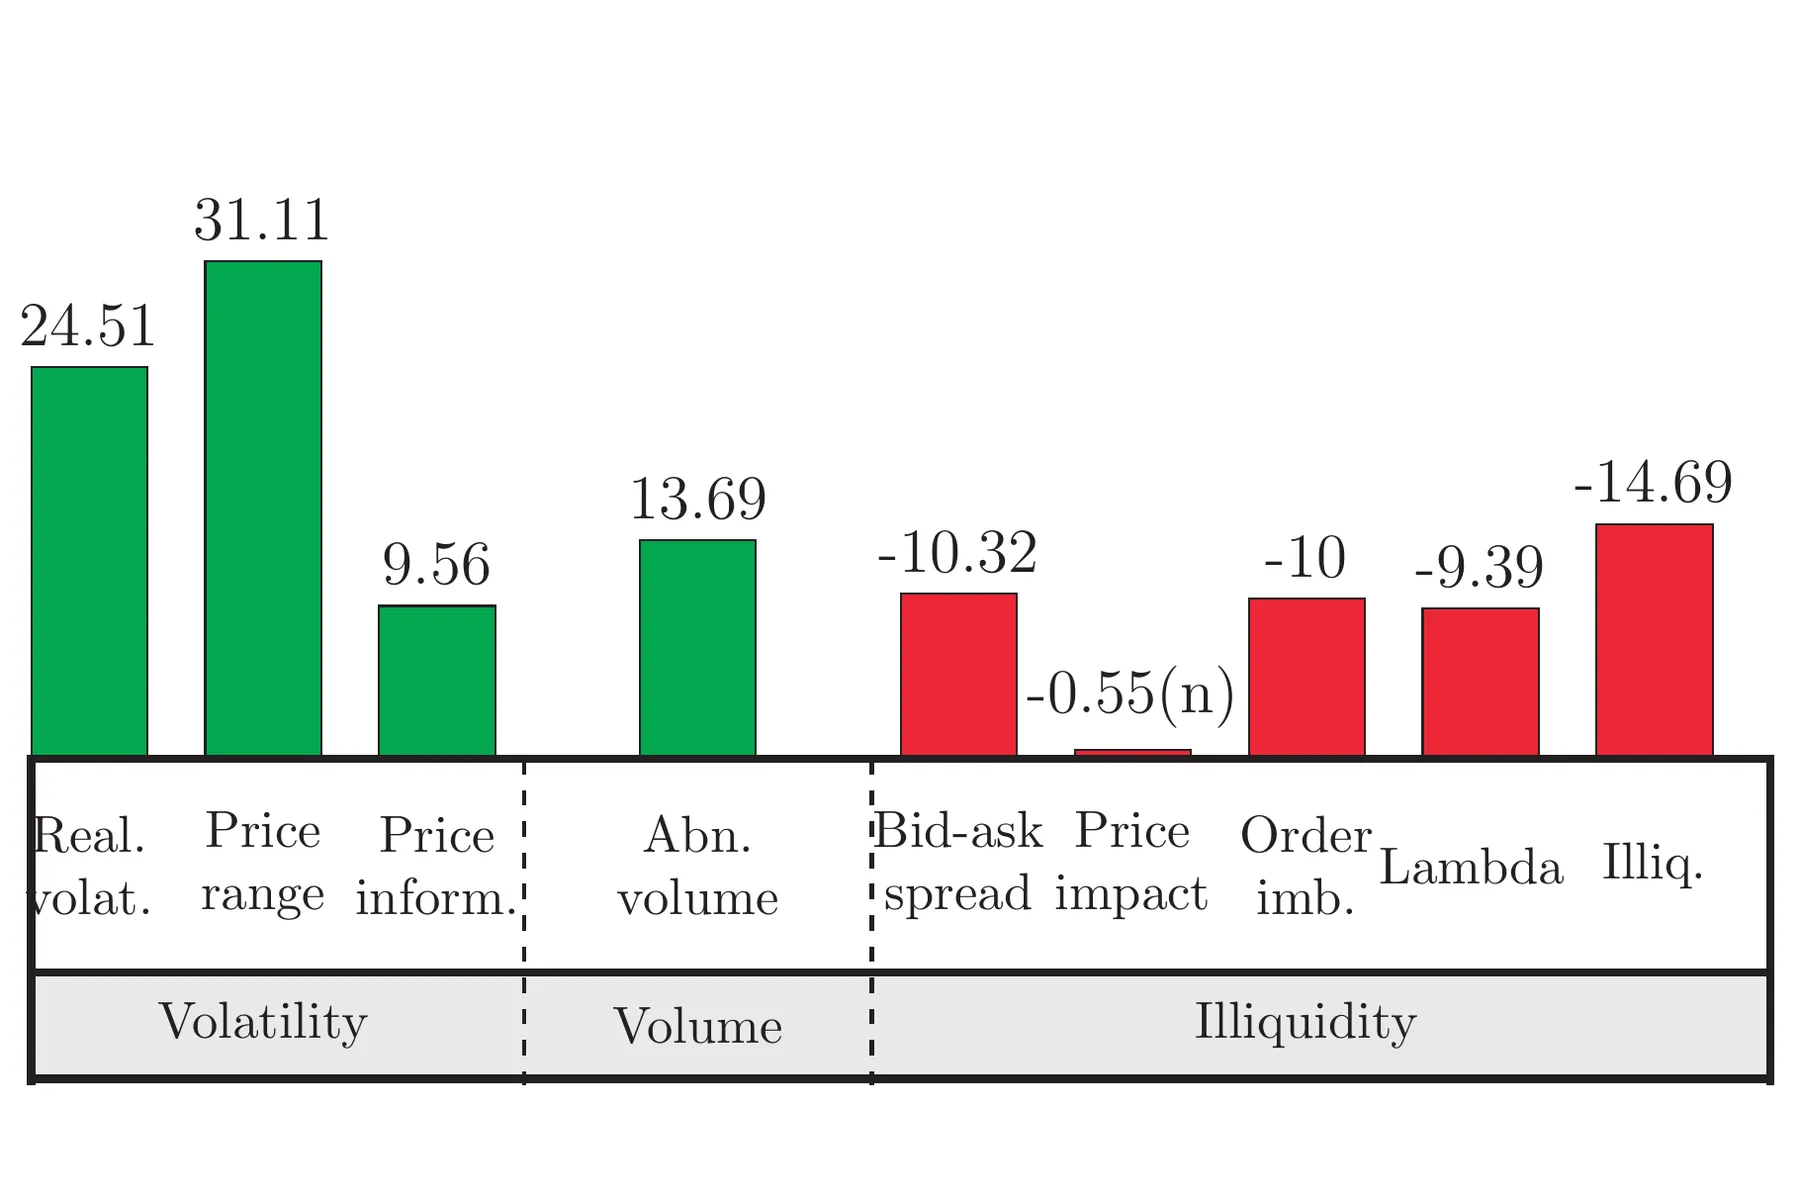
Using over 5,000 trades unequivocally based on nonpublic information about firm fundamentals, we find that asymmetric information proxies display abnormal values on days with informed trading. Volatility and volume are abnormally high, whereas illiquidity is low, in equity and option markets. Daily returns reflect the sign of private signals, but bid-ask spreads are lower when informed investors trade. Market makers' learning under event uncertainty and limit orders help explain these findings. The cross-section of information duration indicates that traders select days with high uninformed volume. Evidence from the U.S. SEC Whistleblower Reward Program and the FINRA involvement addresses selection concerns.
Cite
Marcin Kacperczyk and Emiliano S. Pagnotta (2019). "Chasing Private Information." The Review of Financial Studies 32(12): 4997–5047.
@article{10.1093/rfs/hhz029,
  author  = {Kacperczyk, Marcin and Pagnotta, Emiliano S},
  title   = {Chasing Private Information},
  journal = {The Review of Financial Studies},
  volume  = {32},
  number  = {12},
  pages   = {4997-5047},
  year    = {2019},
  month   = {12},
  doi     = {10.1093/rfs/hhz029},
  url     = {https://doi.org/10.1093/rfs/hhz029}
} Presentations
WFA, NBER LTAM, NBER Asset Pricing SI, FIRS, SED
- 17 Jul 2017 NBER Summer Institute, Asset Pricing, Boston
- 6 Jul 2017 Erasmus Liquidity Conference, Rotterdam
- 5 Jun 2017 Financial Intermediation Research Society (FIRS) Conference, Hong Kong
- 1 Jun 2017 Paul Woolley London School of Economics Conference, London
- 25 May 2017 NBER Long-Term Asset Management, London
- 2015–2016 CEPR conference, London
- 2015–2016 Western Finance Association (WFA), Park City